Two positions sit at the center of that thesis right now: Orbio (@orbiodotso, orbio.so), building an inference capital market, and Auto Protocols / protocol.link (@auto_protocols), building coordination for people and AIs. Both are early. Both are liquid. Both point at markets that can get very large if the core loop works.
Orbio — a capital market for inference
Every serious product now burns inference. Agents, copilots, research loops, customer workflows. The spend is real, recurring, and rising. The procurement layer is still primitive: subscriptions, prepaid credits, opaque markups, keys that do not move like capital.
Orbio treats inference as something that can be priced, held, and transferred.
On the product surface, Orbio is a gateway: one API key, hundreds of models, OpenAI-compatible and OpenRouter-style paths, measured overhead, prompts not stored—billing metadata only. Buyers purchase dollar-denominated credit and spend it through the relay. Holders of $ORBIO sit on the other side of the market. Trading activity funds credit. Unused credit can be offered into a liquidity book at a discount. The Inference Protocol is the loop Yash wrote up: fees become CREDIT, CREDIT stakes or sits in the book. Demand meets supply. Inference clears like a market instead of a subscription form.
That is the thesis in one line: inference becomes a capital market.
If agents buy and spend credit programmatically, if developers route spend through a liquid book instead of a static plan, and if fee flow keeps converting into usable compute, Orbio is not a meme with a FAQ. It is the spot market and clearing layer for a commodity every AI system needs. Yash’s utility-layer read is the same shape: value moves from producing inference to making it consumable—Coca-Cola needed refrigeration, not another syrup plant. The upside case is not “another API wrapper.” It is owning the market structure around a cost center that will keep growing as long as models stay expensive and agents stay hungry.
Orbio is being built in public by Yash (@0x_aster), with a builder track record that includes work around nftperp. Lean team. Fast surface.
The primary public print is Orbio analytics, as of the afternoon of 22 September 2026. The gateway had generated about $166k of backed inference all-time — credit value, not platform revenue — across roughly 303k requests and 21 billion tokens, input plus output. About 488 inference purchases and activations, retail plus onchain, sit behind a combined recorded sales volume of about $13.4k. Orbio’s own docs say that combined volume is not cash revenue. The CREDIT book showed about $36k of face-value liquidity across about 151 open orders. About 347 million ORBIO was staked, roughly 36.5% of supply. Requests ramped from about 6 September; onchain activations picked up mid-month.
An earlier founder snapshot had put book depth near $30k, about $4k a day of consumption, and about $145k buyable. That is a secondary, earlier print, not a second audit. Real gateway usage and a live CREDIT book exist. The scale is still early against Venice and against the illustrative GMV cases below. Fee-funded credit still has to become a habit, not a tape. If the book stays liquid and the gateway stays trusted, Orbio sits under every agent that needs to pay for thought.
Venice — a foil, not a twin
The same question has another public answer: how does an agent, or a developer, secure ongoing inference without a human checkout loop?
Venice is a private, uncensored inference app and API — open models routed, founded by Erik Voorhees, ShapeShift lineage. Privacy is the product wedge. The token is how capacity is owned.
$VVV on Base is the capital and access asset. Stake it for a pro-rata share of Venice API capacity, and for Pro access above a threshold. Platform revenue buys and burns VVV.
DIEM, minted from locked staked VVV, is the capacity unit: one staked DIEM is about a dollar a day of Venice API credit — a perpetual daily allowance while it stays staked, and a token that can trade. The docs are explicit.
That is ownership of capacity inside one private stack. Token value is tightly tied to Venice’s own demand and capacity growth. The product loop is real enough that the market has already paid a mature price for it. As of about 22 September 2026, VVV printed around $31–32 on CoinGecko and DexScreener on Base — circulating market cap on the order of $1.5 billion, FDV on the order of $2.5 billion. Those numbers move. They are a snapshot, not a model.
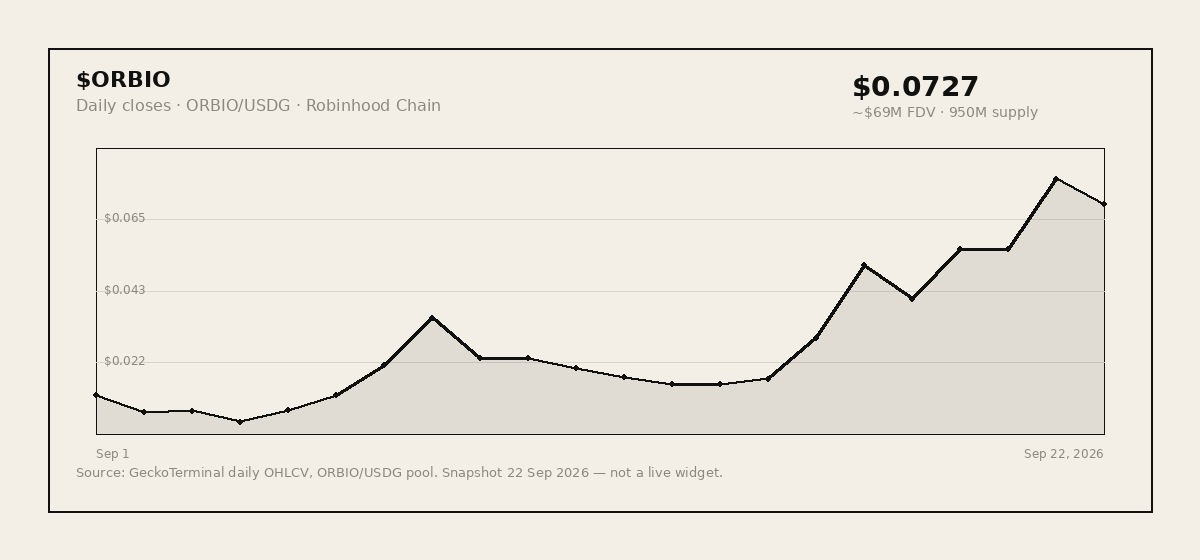
Orbio is a different mechanism at a different stage. It is building a market for dollar-denominated CREDIT that can be traded, discounted, and activated across models through an OpenRouter-style gateway. Fee flow from ORBIO trading funds CREDIT. The book is where unused credit meets buyers. The wedge is liquidity and clearing, not a claim on one lab’s capacity. Against Venice’s billion-scale print, ORBIO’s late-September discovery — about seven cents, about $69 million FDV on 950 million tokens, Robinhood Chain — is still small.
Venice is useful because it proves the category. The market will pay large FDVs for tokenized inference access when the product loop is real. Orbio is a different bet: that inference wants an open credit market, not only stake-for-capacity on one venue — and that agents will buy discounted CREDIT the way traders buy other commodities.
The honest fork is simple. If a Venice-like stake-for-capacity design wins the whole category, Orbio’s book stays niche. If agents need portable, transferable, multi-model credit that clears on-chain, Orbio’s design is the sharper tool.
Auto Protocols — coordination for people and AIs
Software let individuals ship. Crypto let capital coordinate without a firm. Agents will force a third layer: organizations that are not only human.
protocol.link — Auto Protocols — states the product plainly: a coordination platform for people and AIs. A shared vision. Discussion that becomes decisions. Decisions that become tasks. Tasks that move forward through members and agents. Pool skills, tools, and funding. Ship useful work with a community that includes non-human labor.
This is not another chat UI. It is infrastructure for groups that can include agents as first-class workers: humans setting direction, agents proposing and executing tasks, capital and attention pooled against a shared outcome.
The thesis: as agents get competent, the scarce layer is not another model. It is the protocol that lets humans and agents organize, decide, and ship together.
If that becomes default for online teams, DAOs, open-source efforts, and agent swarms, Auto Protocols is early infrastructure for a new kind of firm. The upside case is category-defining: the operating system for mixed human–agent organizations. The risk case is also clear: coordination products die when they are empty rooms. Distribution, trust, and real work loops matter more than manifesto copy.
Auto Protocols is being built by an ex-GMX developer — someone who has already shipped in environments where money, latency, and adversarial users are not theoretical. That background matters for a product that will eventually touch shared resources and automated execution.
Sizing the loops
The loops need a scale, not a slogan. Public market-size reports give the pool. They do not give Orbio or Auto Protocols a revenue line. What follows are illustrative paths—bear, base, bull—against those pools, and for Orbio a fee-and-multiple bridge from GMV to FDV. The bridge is a research case, not a promise.
Orbio: share of the credit book
For inference, the closest public fit is foundation-model API and credit spend, not chips. Menlo Ventures’ 2025 report, The State of Generative AI in the Enterprise, puts U.S. enterprise generative AI at $37 billion in 2025, of which foundation-model APIs are $12.5 billion. Menlo notes that API spend rose from about $3.5 billion in November 2024 as production inference scaled. That scope excludes chips and the major clouds’ model-serving layers on AWS, GCP, and Azure.
Hardware-heavy inference estimates sit much higher—MarketsandMarkets has put AI inference near $106 billion in 2025 and $255 billion by 2030—and we treat those as upper context, not the TAM for a credit book. Secondary summaries of Gartner-style foundation generative-model spend have the category roughly doubling from about $11 billion to $23 billion between 2025 and 2026. The dollars scale if API spend grows. The question for Orbio is share of the routed layer.
Orbio’s wedge is a liquidity book and an OpenRouter-compatible relay for LLM credits. The GMV cases below are annual credit spend that could route through that book, on a $12.5 billion foundation-model API base. If the API pool grows, the same shares imply larger dollars.
Early price discovery on Robinhood Chain put ORBIO near seven cents by late September — about $69 million FDV on 950 million tokens, circulating and fully diluted the same number. The chart is the path from listing into that print. Under the base case below, that price is already ahead of the analytics usage print.
CREDIT book fees are zero at launch. Today’s economics sit on ORBIO trading fees — half treasury, half inference backing — per Yash’s Inference Protocol write-up. The bridge is therefore illustrative: what routed credit GMV could be worth if the protocol eventually took about 2% of that GMV, capitalized at 8× in the bear, 20× in the base, and 35× in the bull, and divided by 950 million tokens. It is not a claim about today’s fee schedule. This calculation also assumes those fees create economic value for ORBIO holders. Protocol revenue is not automatically token-holder cash flow: the fee mechanism, costs, governance, and holder rights would need to support that bridge. Without it, dividing a protocol valuation by token supply does not establish a token price.
- Bear (~0.05% of the API pool): about $6 million GMV. Speculative churn, weak real credit demand, labs keep the book. That case implies roughly $120k of fees and a ~$1 million FDV — about $0.001 a token.
- Base (~0.5–1%): about $60–125 million GMV. A credible discount book; developers and agents route habitually; the fee-to-credit loop works. That case implies about $1.2–2.5 million of fees and a $24–50 million FDV — about $0.025–0.053.
- Bull (~5–10% of the same $12.5 billion API reference pool): about $0.6–1.3 billion GMV. The default liquid credit market for agents, a deep book, durable usage. That case implies about $12–26 million of fees and a $420–910 million FDV — about $0.44–0.96.
What must be true: credits move because someone is shipping. The book is deeper than the token. Agents pay at the spot, not on a monthly invoice. If that fails, the bear case is the honest one.
Auto Protocols: share of executable work
Coordination is a younger, worse-measured category. Incumbents own the chat seats—Microsoft Teams, Slack. Auto Protocols is a protocol for executable work: identity, job, settlement, humans and agents in the same loop.
Adjacent public numbers are team-collaboration tools. Mordor Intelligence has that market near $20.9 billion in 2025 and about $42 billion by 2031. Grand View Research, widely cited, has it near $36 billion in 2024 and about $57 billion by 2030. As a mid-range for collab-adjacent spend that could become agent-mediated work, we use about $25 billion. That is not Auto Protocols revenue. There is no public Auto Protocols token market cap we will invent.
- Bear (~0–0.02%): near-zero sustained jobs. Empty rooms. A manifesto without receipts.
- Base (~0.2–0.5%): about $50–125 million. Crypto and AI-native teams run real jobs on-protocol.
- Bull (~2–5%): about $0.5–1.25 billion of the reference spend pool. The default operating system for mixed human–agent organizations.
What must be true: a person or an agent posts work. Another takes it. The receipt is real. Repeat. If the protocol only describes coordination, the bear case is already written.
A liquid fund does not underwrite a slide that says TAM. It underwrites whether a loop can take a share of a spend pool that is already large and still growing—and whether that share is usage. The rest is theater.
What would change our conviction
- Orbio: repeat paid inference consumption, executable order-book depth, and a funding model that remains viable when token trading slows. Backed credits, purchases, usage, and revenue are different measures.
- Auto Protocols: retained teams completing verifiable jobs, repeat participation, and a clear way to charge for useful work. Collaboration-software spend does not directly measure on-protocol job volume.
- For both: product growth must connect to holder economics. Weak retention, persistent subsidies, or no credible value-capture mechanism would weaken the investment case.
Why both, why liquid, why now
These are not the same company. They are adjacent layers of the same stack.
Orbio answers: how does intelligence get paid for when machines are the buyers? Venice is the foil on that question — own capacity on one stack, or clear credit across many.
Auto Protocols answers: how do humans and machines decide and work together once intelligence is cheap enough to staff?
Baus takes liquid positions when founders are already in motion and the market structure is still early. We are not waiting for a polished Series A narrative. We are underwriting the loop — a share of a growing spend pool, not a deck TAM.
The shared opportunity is recurring demand: agents repeatedly purchasing useful inference, and teams repeatedly completing work. Our conviction should rise with retention, sustainable economics, and demonstrated value capture—not simply with token trading activity.
If you are building in this stack — inference markets, agent-native organization, crypto rails under AI work — send the sharpest version of what you believe.
hello@baus.ai